Improving liquidity: 12 effective measures for your business
Liquidity determines whether you can seize opportunities or are forced to simply react. It dictates whether you can take advantage of supplier discounts, stay calm during price negotiations, and invest when an opportunity arises. That is exactly why it pays not to wait until things get tight to improve your liquidity. In this article, you will find twelve concrete measures to improve your company's liquidity. They are sorted by speed of impact, calculated, and answer the crucial question: Which lever should you pull first?

Executive Summary
- Improving liquidity means making more cash available faster. This is achieved through four levers: reducing expenses, accelerating cash flows, freeing up tied-up capital, and using financing strategically.
- In the first half of 2026, 12,900 companies in Germany filed for insolvency, 7.8 percent more than in the previous year and the highest level since 2013 (Creditreform, 2026). 20 percent of companies currently report liquidity bottlenecks (DIHK, 2026).
- The fastest levers take effect within one to three weeks: prioritizing investments, invoicing immediately, and consistently following up on outstanding items.
- The largest single lever is usually working capital. Reducing your days sales outstanding (DSO) by 15 days frees up approximately 98,600 euros on 2.4 million euros in revenue.
- External financing is the last step, not the first. 26 percent of companies now rate access to credit as difficult (KfW, 2026).
- A one-time cleanup is not enough. Since 2021, Section 1 of the StaRUG (Corporate Stabilization and Restructuring Act) has required the management of limited liability companies to continuously monitor for early signs of crisis.
What does it mean to improve liquidity?
A company's liquidity describes its ability to meet all payment obligations on time. Improving it means having more money available on a permanent basis and being able to access it sooner. It is therefore the central control variable in liquidity management. This is different from profit. A company can be profitable and still become insolvent. It is enough for money to be tied up at the wrong time.
In short: Improving liquidity means increasing available cash and bringing forward the timing of its availability. There are four levers for this: reducing expenses, accelerating incoming payments, freeing up tied-up capital, and using financing strategically. The key is not to implement as many measures as possible, but the right ones in the right order.
Short-term liquidity means: You are solvent at all times over the next twelve months, even if salaries, tax payments, and loan installments fall due in the same week. Long-term liquidity means: Your solvency holds up over several years, based on realistic assumptions regarding growth, investments, and financing structure.
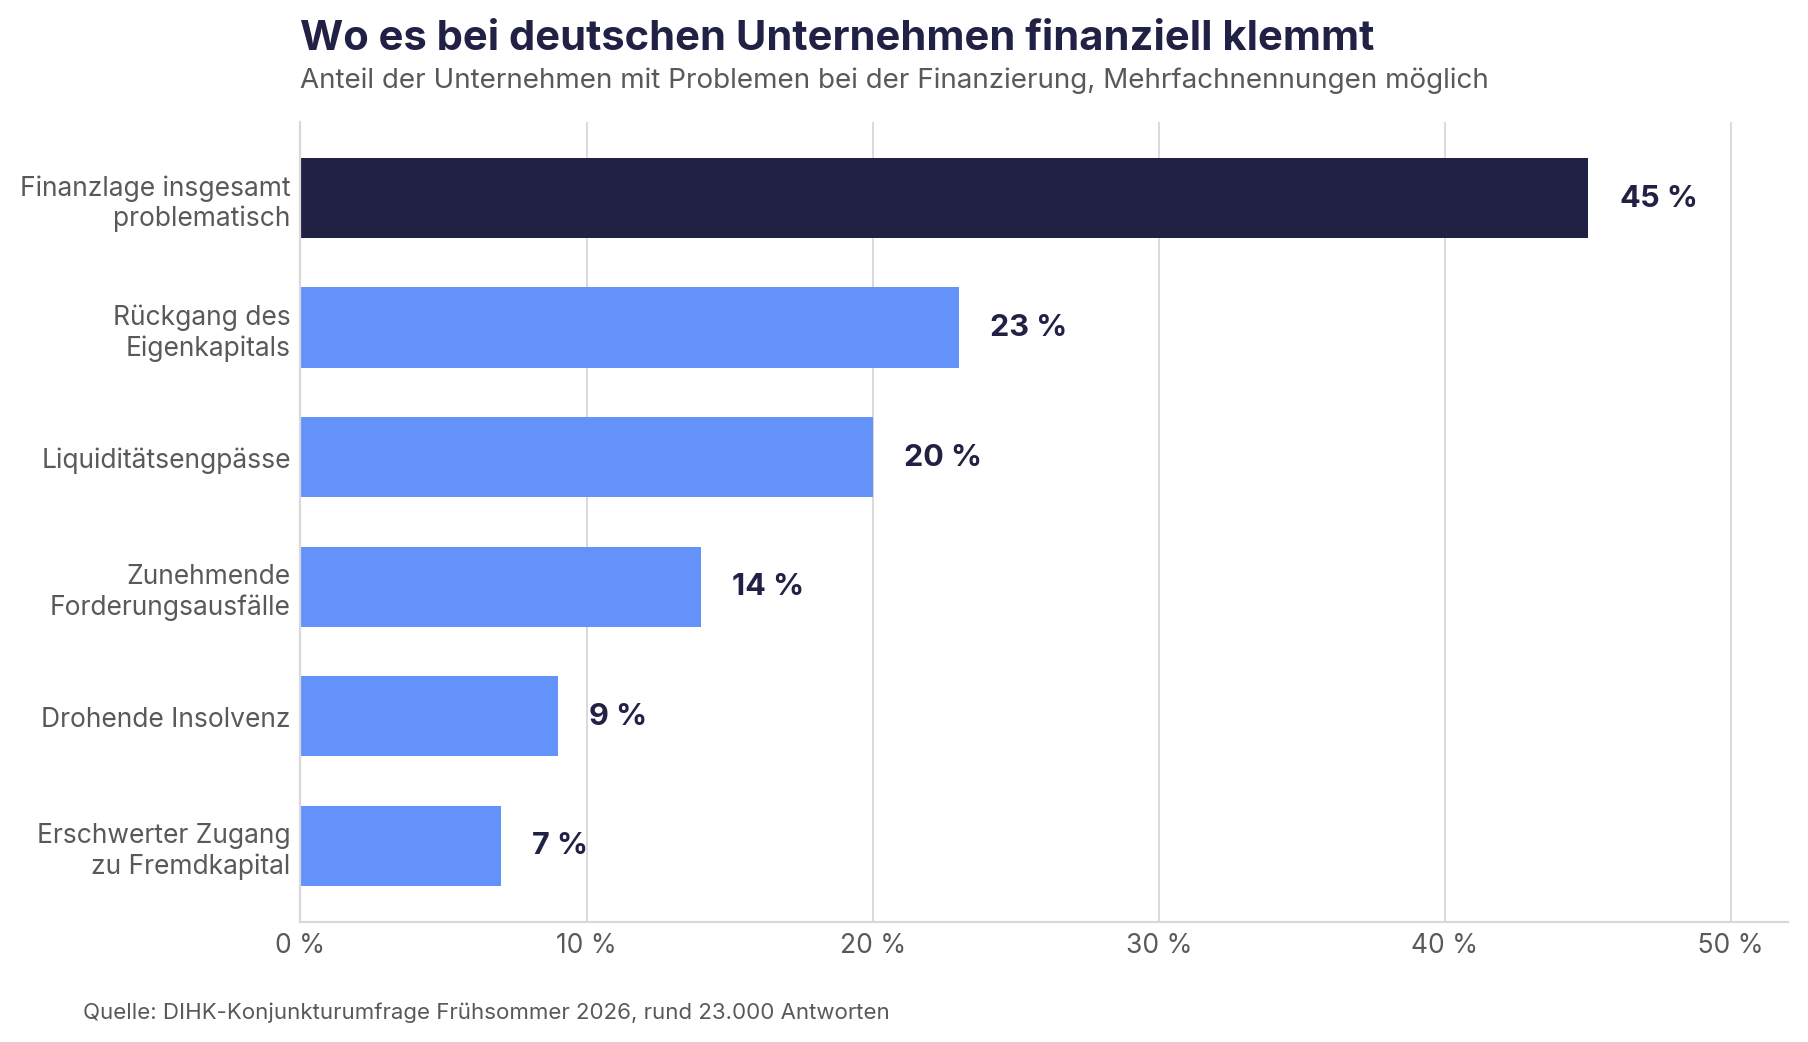
The current economic context makes this topic more urgent. In the first half of 2026, 12,900 companies filed for insolvency, an increase of 7.8 percent compared to the previous year and the highest figure since 2013 (Creditreform, 2026). 81.0 percent of these were businesses with fewer than ten employees. At the same time, the financial situation is deteriorating across the board. In the DIHK business survey with around 23,000 responses, 45 percent of companies reported a problem with their financial situation, up from 43 percent in the previous survey. 20 percent specifically mentioned liquidity bottlenecks, 23 percent a decline in equity, and 14 percent increasing bad debts (DIHK, 2026). For the full year 2025, the number of corporate insolvencies was 23,900 (Creditreform, 2025). For 2026, around 24,500 cases were forecast the previous year (Allianz Trade, 2025). If you extrapolate the first half of 2026, the actual number is likely to be higher.
How do you know that you need to improve your liquidity?
There are three clear signals: your liquidity ratios are significantly below the benchmarks, your operating cash flow is negative, or you are regularly overdrawing your current account to pay salaries. Each of these signals alone is reason enough to take a closer look at the numbers.
In short: Check three early indicators. First, liquidity ratios 1 and 2, which show whether you can cover short-term liabilities. Second, operating cash flow, which shows whether day-to-day business is generating cash. Third, the utilization of your credit line. Anyone who consistently uses a large portion of it no longer has a buffer for surprises.
The three liquidity ratios and what they tell you
Liquidity ratios are balance sheet metrics calculated at a specific point in time. They show how well you can cover your short-term liabilities with available funds.
- Cash Liquidity (Liquidity Ratio 1): (Cash and cash equivalents ÷ short-term liabilities) × 100. Typical benchmark: 10 to 30 percent. It shows you whether you can pay immediately without waiting for incoming payments.
- Quick Ratio (Liquidity Ratio 2): ((Cash and cash equivalents + short-term receivables) ÷ short-term liabilities) × 100. Typical benchmark: 100 to 120 percent. It shows you whether receivables and bank balances together cover short-term debts.
- Current Ratio (Liquidity Ratio 3): (Current assets ÷ short-term liabilities) × 100. Typical benchmark: 120 to 200 percent. It shows you whether total current assets, including inventory, cover short-term debts.
These values vary depending on the source and industry. A retail business with high inventory will naturally have a different current ratio than an agency without inventory. The trend over several quarters is more important than the absolute value.
If the quick ratio falls significantly below 100 percent, it means: even if all customers pay on time, there is not enough money to cover short-term liabilities. This is the point where taking action is no longer an option, but a necessity.
Reading tip: Our guide Calculating Liquidity shows you how to calculate each of these metrics step by step.
Why liquidity ratios alone are not enough
Liquidity ratios have a weakness: they are a snapshot. They show what the situation looked like on the balance sheet date. They do not show what it will look like on the 15th of the next month, when salaries, advance VAT payments, and leasing installments all fall due at the same time.
This is precisely why forward-looking liquidity planning complements these key figures. It shows not just the current state, but the trajectory. Only this combination of key figures and forecasts makes effective management possible.
Where is your money tied up? The Cash Conversion Cycle
The Cash Conversion Cycle shows in days how long your money is tied up in the business process, from purchasing to receipt of payment. It is the most precise indicator of where liquidity is lying dormant. Most guides on improving liquidity simply overlook it.
In short: The Cash Conversion Cycle consists of three components. DSO measures how long it takes for customers to pay. DIO measures how long goods or work-in-progress remain in inventory. DPO measures how long you take to pay your own suppliers. The formula is: CCC = DSO + DIO - DPO. The lower the value, the less capital is tied up.
You can calculate the three components as follows:
- DSO (Days Sales Outstanding): (Trade receivables ÷ annual revenue) × 365. This is the average payment duration of your customers in days.
- DIO (Days Inventory Outstanding): (Inventory or work-in-progress ÷ cost of materials) × 365. This is the average duration of capital tied up in inventory in days.
- DPO (Days Payables Outstanding): (Trade payables ÷ cost of materials) × 365. This is the average payment duration to suppliers in days.
A note on accuracy: Receivables are recorded gross on the balance sheet, while revenue is reported net. The DSO calculated this way is therefore slightly too high. For comparisons over time, this does not matter as long as your calculation method remains consistent.
The payment behavior in the market shows why this is relevant. 57 percent of B2B invoices in Germany are paid late, and 10 percent of receivables have recently proven to be uncollectible (Atradius, 2024). In the construction industry, the average collection period is 87 days (Atradius, 2024). Every day you can shave off here is hard cash.
Which measures are most effective?
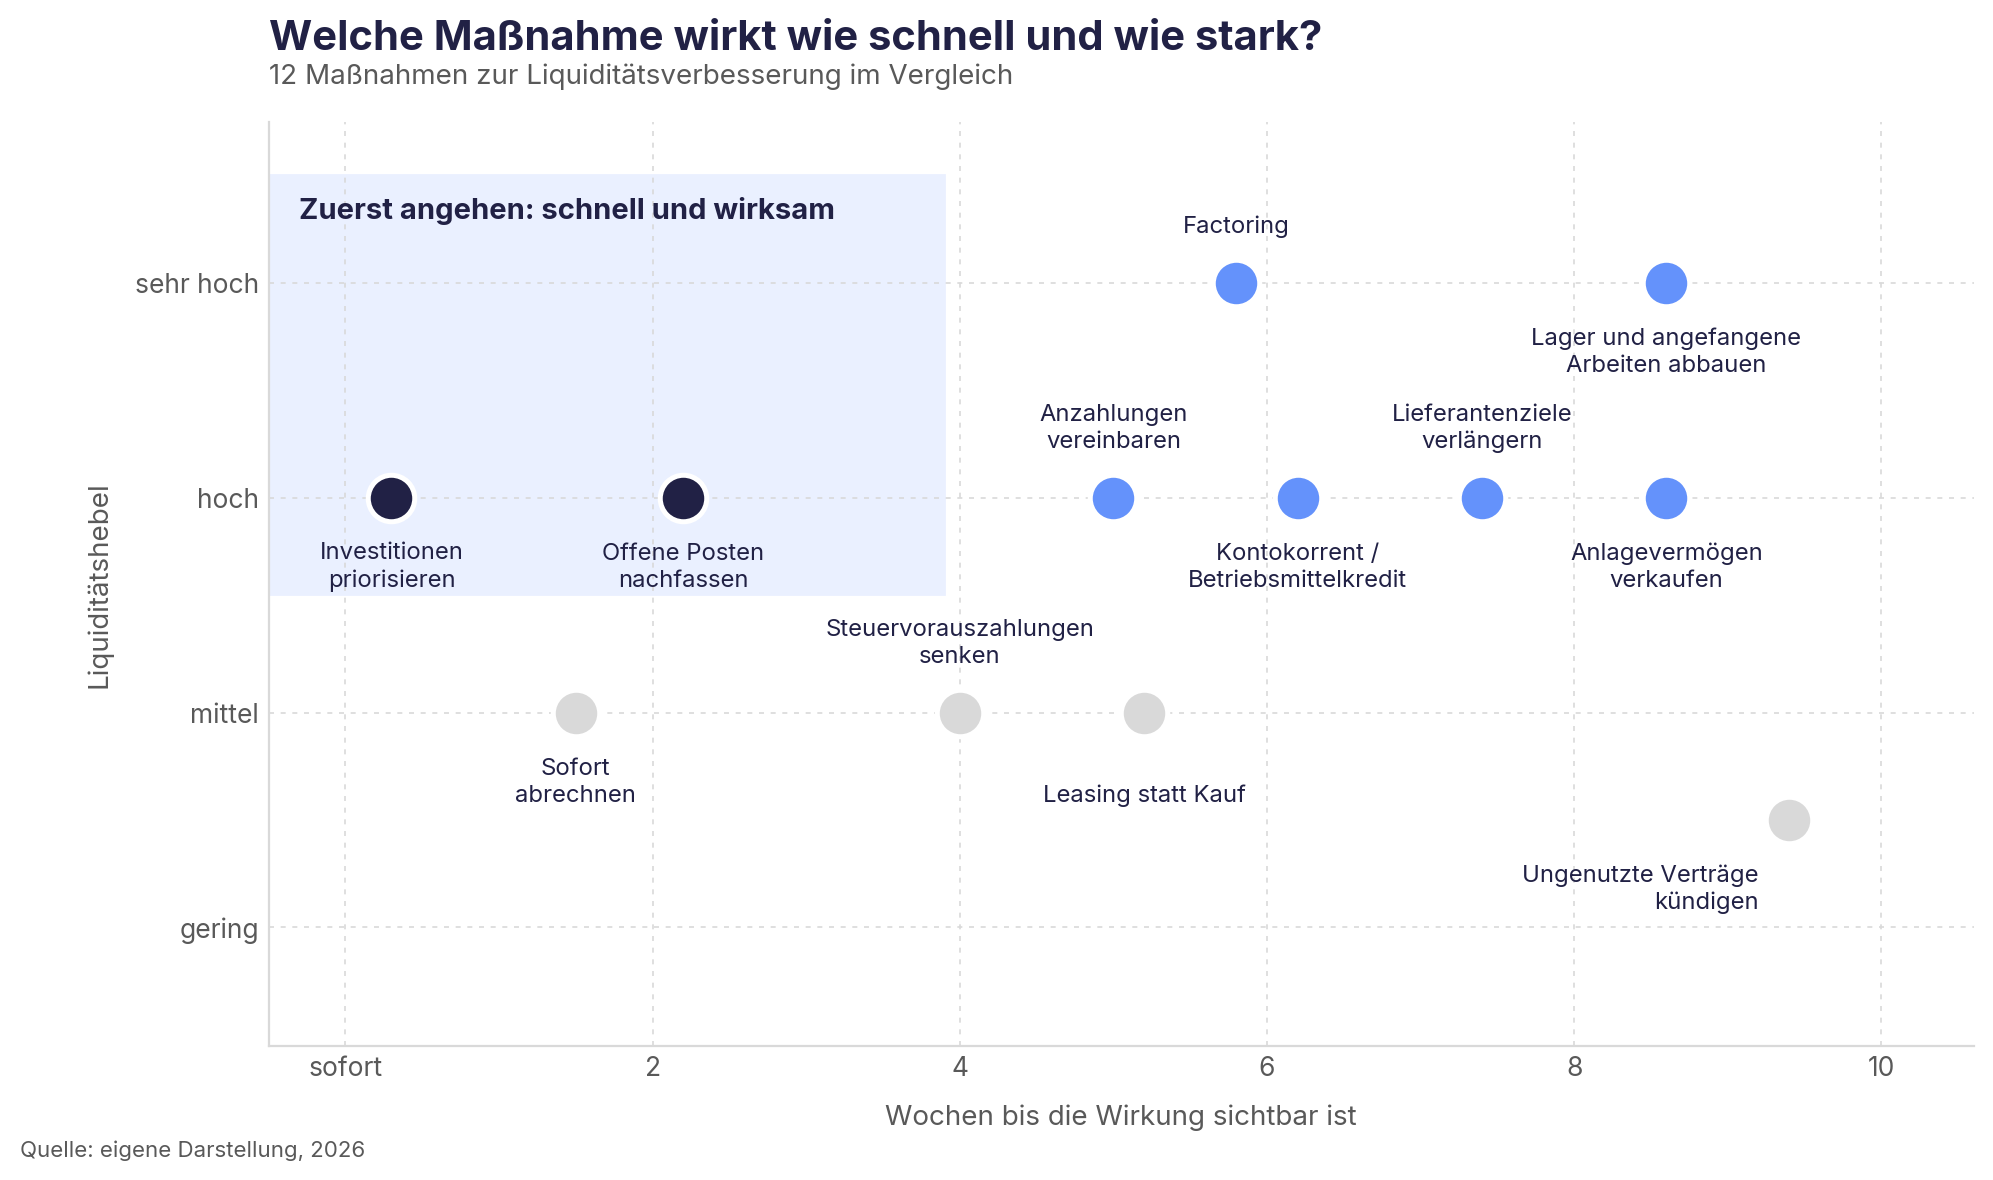
The most effective measures are those you can implement without negotiating with third parties: postponing investments, invoicing immediately, and following up on outstanding items. The greatest leverage lies in working capital, but these measures take several weeks to months to take effect. External financing also has a substantial impact, but it costs money in the long run and does not solve any structural problems.
In short: Categorize measures according to three criteria: how quickly they take effect, how great the leverage is, and what price you pay for them. Immediate measures like faster invoicing cost nothing and work in days. Working capital measures free up the largest amounts but take four to twelve weeks. Financing provides breathing room but increases fixed costs.
The twelve measures in detail, sorted by speed of impact:
- Prioritize or postpone investments. Immediate impact, high leverage, low effort. Ensure you do not create a bottleneck for growth.
- Issue invoices immediately after service delivery. Impact in 1 to 2 weeks, medium leverage, low effort. The process must be sustainable, not just a one-off.
- Follow up on outstanding items consistently. Impact in 1 to 3 weeks, high leverage, low effort. Follow up early and politely, not just after the second reminder.
- Adjust advance tax payments. Impact in 2 to 6 weeks, medium leverage, low effort. Only works if you can prove lower earnings.
- Agree on down payments and progress billing. Impact in 2 to 8 weeks, high leverage, medium effort. Can only be enforced for new orders.
- Leasing instead of buying. Impact in 2 to 8 weeks, medium leverage, medium effort. Expect higher total costs over the term.
- Overdraft or working capital loan. Impact in 2 to 10 weeks, high leverage, high effort. Costs interest and requires collateral and a credit check.
- Factoring. Impact in 3 to 8 weeks, very high leverage, high effort. Fees permanently reduce your margin.
- Extend payment terms with suppliers. Impact in 4 to 8 weeks, high leverage, medium effort. May cost you early payment discounts and favorable terms.
- Reduce inventory and work-in-progress. Impact in 4 to 12 weeks, very high leverage, medium effort. Your ability to deliver must not suffer.
- Sell or lease out fixed assets. Impact in 4 to 12 weeks, medium to high leverage, medium effort. Consider book value, remaining useful life, and tax on capital gains.
- Cancel unused contracts and subscriptions. Impact in 1 to 3 months, low to medium leverage, low effort. Check notice periods, as the impact is delayed.
This order is not a dogma, but a good rule of thumb: work your way from top to bottom. Anyone who starts by talking to the bank instead of first checking their own working capital is giving away negotiating power and paying interest for money that is already available within their own company.
How do you reduce your expenses without slowing down the business?
The most direct measure to improve liquidity is to cut expenses. The difference between effective and harmful cost-cutting is simple. Are you cutting costs that generate revenue, or costs that are merely a habit?
In short: Divide your costs into three groups. Group one generates direct revenue and remains untouched. Group two secures operations and is renegotiated. Group three is habit, such as unused software licenses, duplicate insurance policies, or subscriptions without users. Cut group three immediately, and renegotiate group two.
Three approaches deliver the best results in practice:
Renegotiate supplier contracts. Reviewing existing framework agreements often reveals prices that haven't been adjusted in years. Ask for a competitive quote before you negotiate. This gives you a solid foundation without compromising quality.
Clean up your software and subscription landscape. Many SMEs pay for licenses for employees who are long gone, or use two tools with the same function in parallel. This often amounts to hundreds of euros a month flowing out with nothing to show for it.
Prioritize investments instead of cutting them across the board. A blanket investment freeze works in the short term but costs you competitiveness in the medium term. It is more sensible to test every planned investment with a simple question: When will this expenditure start generating a return? Anything that generates a return within twelve months stays. Everything else is postponed.
It is important to look at the long-term impact. Anyone who slashes sales will improve liquidity in the short term but worsen it in six months. That is why every cost-cutting measure must be accompanied by the question of how it will affect cash flow over a twelve-month horizon.
How do you optimize your payment terms on both sides?
Payment terms are the lever you have the most direct control over. The principle: bring money in sooner and pay it out later. Customer relationships and supplier terms must not suffer as a result.
In short: Work on both sides simultaneously. On the customer side, shorten payment terms, agree on down payments, and invoice immediately. On the supplier side, extend payment terms or take advantage of early payment discounts where it makes financial sense. Every day of difference between the two sides has a direct impact on your available liquidity.
Shortening payment terms for customers
The quickest win rarely lies in the payment term itself, but in the timing of the invoicing. For example: the service is provided on the 3rd, but not billed until the end of the month. You lose up to 28 days before the clock even starts ticking.
Three levers have an immediate effect:
- Invoice immediately. Invoices should go out the day after the service is provided, not collected at the end of the month.
- Agree on down payments and progress billing. For projects of a certain size, it is often possible to agree on a staggered payment schedule, such as one-third upon order placement, one-third upon interim acceptance, and the remainder upon final acceptance.
- Follow up early and politely. A quick call three days before the due date is more effective than three reminders afterward and does not strain the customer relationship.
In the event of late payment, statutory regulations regarding default interest and late payment fees also apply. Knowing them makes you a more confident negotiator.
Reading tip: Our article on late payment and your rights explains what rights you have in the event of late payment and how to enforce them.
Extending payment terms with suppliers
On the expenditure side, the opposite applies: pay as late as agreed, but never later. Extending a payment term from 14 to 30 days is often worth discussing with long-standing suppliers, especially if you guarantee purchase volumes in return.
You should keep two limits in mind. First: if you hold off paying your suppliers without prior agreement, you risk being put on prepayment terms, receiving worse conditions, and being reported to credit agencies. Second: extended payment terms often mean losing out on early payment discounts, and those discounts are more valuable than they appear.
Calculating early payment discounts correctly
An early payment discount acts like a small rebate, but in reality, it is a high-interest short-term loan transaction. If you forgo the discount, you are essentially taking out an expensive loan from your supplier. The calculation is simple:
Annual discount interest rate = (Discount rate × 100) ÷ (100 - Discount rate) × 360 ÷ (Payment term - Discount period)
Example: 2 percent cash discount for payment within 10 days, otherwise 30 days net.
(2 × 100) ÷ 98 × 360 ÷ 20 = 36.7 percent annual interest
This is the standard linear projection. When calculated with compound interest, the rate is actually around 44 percent.
In other words: As long as your overdraft facility costs less than 36.7 percent—which is practically always the case—it is worth taking the cash discount and using your credit line if necessary. Conversely, it is almost never wise to forgo a cash discount to preserve liquidity. The price for doing so is too high.
The benchmark has recently moved upward: On September 10, 2026, the European Central Bank decided to raise all key interest rates by 25 basis points; the deposit facility rate has been at 2.50 percent since September 16 (ECB, 2026). Overdrafts tend to become more expensive as a result, but they remain well below the 36.7 percent from the example. Therefore, rising interest rates do not weaken the cash discount argument; they only narrow the gap.
How do you free up tied-up capital?
Tied-up capital is money that belongs to you but is not available. It is locked in inventory, work in progress, and fixed assets. This is usually the single biggest lever for improving liquidity. No interest is incurred here, and no one else needs to approve it.
In short: Check three types of assets. First, inventory and goods that have been sitting for more than six months. Second, work in progress that has not yet been invoiced. Third, machinery, vehicles, or space that sits idle for the majority of the year. Each of these items can be converted into liquidity without harming ongoing operations.
Inventory and work in progress
In trade and production, the lever is in the warehouse. A simple ABC analysis quickly shows which items drive revenue and which have been tying up capital for months. For slow-moving items, there are three paths: clearance sales with discounts, returning them to the supplier, or bundling them with fast-moving items.
In the service and project business, the equivalent is "work in progress": hours worked that have not yet been billed. They do not appear on any inventory list and are therefore often overlooked, yet they tie up capital just the same. The lever here is the billing frequency: billing monthly instead of at the end of a project significantly shortens the duration of the capital tie-up.
Selling, renting out, or leasing back fixed assets
Unused machinery, vehicles, or warehouse space tie up capital and cause ongoing costs. Three options:
- Sale, if the asset is no longer needed
- Rental, if it is only used intermittently
- Sale-and-lease-back, if you still need it but want to free up the tied-up capital
Sale-and-lease-back provides immediate liquidity, but it is more expensive over the term than ownership. One point that is often overlooked is important: If the sale price is higher than the book value, hidden reserves are realized, and the book profit is immediately taxable. The actual cash inflow is therefore lower than the sale price. This instrument makes sense if you invest the freed-up capital in something that generates more than the leasing costs. As a mere gap-filler, it is an expensive business.
How do you collect outstanding receivables faster?
Outstanding receivables are money you have already earned but have not yet received. 57 percent of B2B invoices in Germany are paid late (Atradius, 2024). For most companies, consistent follow-up is therefore the fastest way to improve liquidity.
In short: Focus on prevention rather than escalation. Check the creditworthiness of new customers before accepting orders, fix payment terms in writing, issue invoices accurately and immediately, and send a friendly reminder three days before the due date. Anyone who only takes action after the second reminder has easily lost six weeks of liquidity.
The most effective steps in order of impact:
- Check creditworthiness before accepting an order. A credit report costs a few euros and prevents losses that would cost many times more.
- Issue invoices without errors. Incorrect order numbers, missing descriptions of services, or the wrong contact person are the most common reasons why invoices get stuck in a customer's approval process.
- Remind before the due date. A short message three days prior is a service, not a dunning notice, and works better than any escalation afterward.
- Follow up consistently and on a fixed schedule. A clear process with defined deadlines is more effective than ad-hoc individual decisions.
- Consider factoring if receivables are structurally slow to pay. With factoring, you sell outstanding receivables to a service provider. You are not paid the full amount, but rather an advance of usually 80 to 90 percent. The withheld amount follows once the customer has paid. Two variants must be distinguished: With genuine factoring, the provider assumes the default risk; with non-genuine factoring, it remains with you, making it economically equivalent to a loan. Calculate the fee rate as an annual interest rate and compare it with your financing alternatives.
When is external financing the right lever?
External financing makes sense when you are pre-financing an investment or bridging a predictable gap. It is the wrong lever if it is masking a structural problem in your working capital. In that case, the problem is merely postponed and becomes more expensive.
In short: Before every financing discussion, check two questions. First: Is the gap one-off and predictable, or recurring? Second: Have I exhausted all internal levers? Access to credit has become more demanding. 26 percent of companies rate it as difficult, and for businesses with less than one million euros in revenue, that figure is 33 percent (KfW, 2026).
The KfW corporate survey also shows why credit discussions fail: 77 percent of the affected companies report increased collateral requirements, 76 percent report stricter creditworthiness criteria, and 69 percent report higher disclosure requirements (KfW, 2026). For short-term loans, the failure rate is 23.4 percent (KfW, 2026).
This leads to a practical consequence: the quality of your documentation is a deciding factor in whether you get approved. A comprehensible, rolling liquidity plan with scenarios is no longer a bonus—it is your ticket to the table. Anyone who can demonstrate in a bank meeting how cash flows will develop over the next twelve months and what happens in the event of a 20 percent drop in revenue negotiates from a much stronger position.
An overview of common instruments:
- Overdraft facility: suitable for short-term fluctuations during the month. Immediately available and flexible, but carries the highest interest rate of any debt financing.
- Operating loan: suitable for predictable financing needs over several months. Fixed framework and better terms, but requires interest payments and collateral.
- Leasing: suitable for purchasing machinery, vehicles, or IT equipment. No high one-off expenditure, but higher total costs over the term.
- Factoring: suitable for structurally long payment terms. Receivables are turned into cash immediately, but the fee per invoice reduces your margin.
- Government grants: suitable for investments, digitalization, and consulting. They offer interest rate advantages or subsidies, but require application effort and are subject to deadlines.
- Equity capital: suitable for growth financing. No repayment pressure, but you give up company shares in return.
A note on the equity side: The average equity ratio in the German SME sector is 30.7 percent, while 28.4 percent of SMEs are undercapitalized with less than 10 percent equity (KfW, 2025). For undercapitalized businesses, additional debt is rarely the solution because it further worsens the ratio and makes future financing more difficult.
Which tax levers can improve your liquidity?
Tax planning is an underestimated way to improve liquidity. It shifts payment dates without increasing the tax burden. Three approaches can take effect within a few weeks.
In short: Check three points with your tax advisor. First, reducing advance payments if your earnings are lower than the previous year. Second, actual-taxation for VAT, where you only remit the tax after receiving payment. Third, a permanent extension of the filing deadline, which pushes your advance return back by one month.
Adjusting advance payments. Income, corporate, and trade tax advance payments are based on the previous year's results. If the current year is lower, you can apply for a reduction. A reliable projection is necessary, and this is exactly where well-maintained planning pays off.
Actual taxation instead of accrual-based taxation. With accrual-based taxation, you remit VAT as soon as the invoice is issued—potentially weeks before the customer pays. With actual taxation, it only becomes due after payment is received. For eligible companies, this is a permanent liquidity advantage equal to the VAT on all outstanding receivables.
Using a permanent deadline extension. This shifts the submission and payment of the VAT advance return by one month. For monthly returns, a special advance payment equal to one-eleventh of the previous year's advance payments must be made. This is credited against the December return, which, due to the deadline extension, is not due until February of the following year.
All three points should be discussed with your tax advisor, as they are subject to specific requirements. The effort is minimal, but the effect is often four figures or higher.
Practical example: How an agency frees up 133,100 euros in liquidity
Numbers make the difference tangible. The following example shows a medium-sized agency that does not take out a single new loan and yet frees up a six-figure sum.
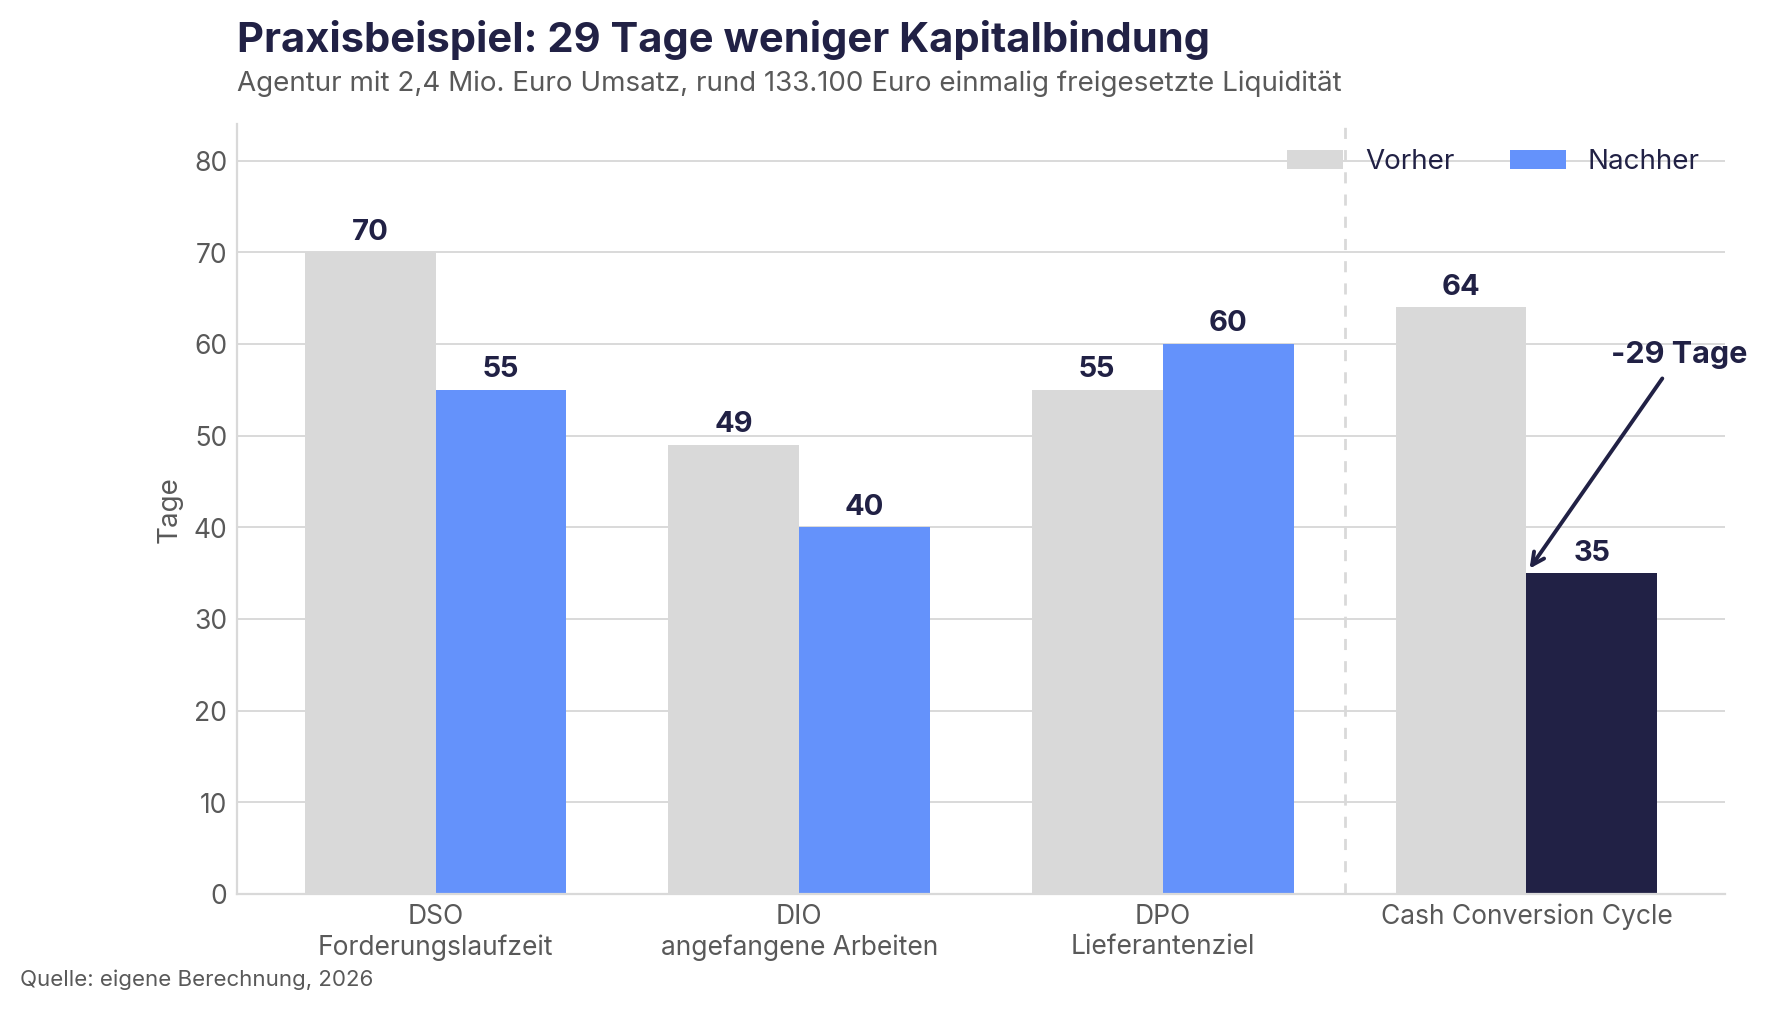
Initial situation: Annual revenue of 2,400,000 euros, expenses for external services and materials of 900,000 euros. This results in daily revenue of approximately 6,575 euros and daily expenses of approximately 2,466 euros.
The agency takes action in three areas:
- DSO (receivables turnover) from 70 to 55 days: through down payments, immediate invoicing, and a reminder before the due date.
- DIO (work in progress) from 49 to 40 days: through monthly rather than project-based billing.
- DPO (supplier payment terms) from 55 to 60 days: through renegotiation with the three largest service providers.
Result: The Cash Conversion Cycle drops from 64 to 35 days. That is 29 days less capital tied up.
What this means in euros:
- 15 days less DSO × 6,575 euros daily revenue = approx. 98,600 euros
- 9 days less DIO × 2,466 euros daily expenses = approx. 22,200 euros
- 5 days more DPO × 2,466 euros daily expenses = approx. 12,300 euros
- Total: approx. 133,100 euros in one-time released liquidity
The DIO impact is calculated conservatively here, as work in progress is valued at cost rather than the final invoice amount. The actual effect of faster billing is usually higher.
In addition, there is the expense side: three unused software licenses and a duplicate insurance policy result in 1,100 euros per month, or 13,200 euros in ongoing annual savings.
An important note for context that most guides omit: The 133,100 euros is a one-time effect. It occurs because capital is released from working capital once. After that, the benefit remains as long as the new values are maintained, but it does not continue to grow. The 13,200 euros in cost savings, however, take effect every year. Together, both provide the agency with room to maneuver without paying a cent in interest.
Reading tip: Our liquidity planning for agencies guide shows how agencies with project-based business plan their liquidity.
Why isn't a one-time cleanup enough?
Because liquidity is not a static state, but a movement. A cleanup gives you breathing room once. Without ongoing planning, DSO, inventory levels, and cost structures will fall back to their old levels within a few quarters. Improving liquidity is therefore not a project, but a routine.
In short: The measures in this article only have a lasting effect if you continuously monitor their key performance indicators. Rolling liquidity planning shows you bottlenecks four to twelve weeks in advance—at a time when you can still choose between options instead of having to take the most expensive one.
For limited liability companies, this has not only been sound business practice since 2021, but a legal requirement. Section 1 of the StaRUG obliges management to continuously monitor developments that could threaten the company's continued existence, to take appropriate countermeasures, and to inform the supervisory bodies. In practice, a planning horizon of 18 to 24 months is recommended for this. In the event of a breach of duty, there is a risk of civil liability towards the company (Federal Ministry of Justice, 2021).
Two planning horizons have proven effective:
- The 13-week plan for operational management. It is accurate to the week and shows whether there will be enough money for salaries and VAT in week 7. It has established itself as the standard because a quarter is far enough ahead to take countermeasures and close enough to be reliably planned.
- The rolling 18- to 24-month plan for strategic decisions: investments, hiring, financing needs. This horizon also covers the expectations set out in Section 1 of the StaRUG.
In addition, there are scenarios. A base case, a worst-case scenario with 20 percent less revenue, and a best-case scenario show you not only where you stand, but also how much of a buffer you have before things become critical.
Reading tip: You can find the complete structure for liquidity planning, including a template, in our guide to liquidity planning.
Excel or software: How do you plan your liquidity?
Excel works for getting started, but reaches its limits as soon as multiple accounts, recurring entries, and scenarios come into play. A survey of around 1,500 finance managers shows just how big the difference is: for companies with previously weak forecast quality, uncertainty about their own cash flow dropped from 68 to 17 percent after introducing automated processes. Six out of ten CFOs now use AI-supported tools in working capital management (PYMNTS, 2026).
In short: Excel is useful as long as you have one account and a few planning items. As soon as multiple bank accounts, ongoing updates, and scenarios are added, the maintenance effort becomes the real problem. Software with bank integration handles data maintenance and turns planning into active management.
The practical difference:
- Data timeliness: In Excel, you import manually, usually monthly. Liquidity planning software is updated daily via bank integration.
- Maintenance effort: Excel costs you several hours per month; software runs largely automatically.
- Scenarios: In Excel, these are file copies that are difficult to compare. Software calculates best, base, and worst-case scenarios in parallel.
- Error susceptibility: High in Excel due to formulas and manual entries. Low in software because data comes directly from the source.
- Multiple accounts and companies: Excel quickly becomes confusing; software shows you a consolidated overall view.
Tidely is one such solution for SMEs, startups, and mid-sized companies. The software connects to over 5,000 banks, automatically categorizes payments, and creates an auto-forecast for the next 24 months based on the last twelve months. The 13-week plan can be generated with one click, you can compare scenarios side-by-side, and reports for banks or advisory boards are available as PDF or Excel at the push of a button. Onboarding, including your first forecast, takes about 15 minutes. Tidely is developed and hosted in Germany, is GDPR-compliant, and ISO 27001-certified.
Reading tip: For a neutral overview of the market, check out our comparison of the best cash flow management software.
Which mistakes cost you the most liquidity?
Five patterns appear again and again in practice. They cost more money than any missed savings measure, and they render every liquidity improvement measure ineffective.
- Confusing profit with liquidity. A good annual result says nothing about whether there is enough in the account on the 28th. The DIHK economic survey shows how far apart the two are: 20 percent of companies report acute liquidity bottlenecks, but only 9 percent see insolvency as a threat (DIHK, 2026). The bottleneck comes long before the existential crisis, and that is exactly where it is decided whether it remains manageable.
- Planning too late. Anyone who only starts planning when the credit line is maxed out no longer has a choice between options, but takes what is available. This is consistently the most expensive option.
- Looking only at costs. The expenditure side is visible and feels like taking action. However, the greater lever almost always lies in working capital, which no bank statement shows.
- Forgoing early payment discounts to save liquidity. As the calculation above shows, this is equivalent to financing at around 36.7 percent per year.
- Implementing measures without checking for side effects. Stalling suppliers worsens terms, cutting the sales budget lowers revenue in six months, and factoring permanently costs margin. Every measure has a price, and that belongs in the decision-making process.
Reading tip: Learn how to identify bottlenecks early and take countermeasures in our article Avoiding liquidity bottlenecks.
Conclusion: Improving liquidity means gaining room to maneuver
Improving liquidity is not just a crisis measure; it is a core management task. Knowing exactly how much cash is available over the next thirteen weeks allows you to negotiate better with suppliers, take advantage of early payment discounts, invest at the right time, and approach bank meetings with confidence.
The order of operations determines the impact. Start with measures you can implement on your own: issue invoices immediately, follow up on outstanding receivables, and cut unnecessary costs. Then, address working capital, which offers the greatest leverage. Review tax planning options. Only turn to external financing once internal sources are exhausted. This way, you avoid paying interest on money that is already tied up in your business.
To ensure lasting results, you need ongoing planning rather than a one-time cleanup. That is exactly what Tidely is built for: connect your bank accounts, generate forecasts in 15 minutes, compare scenarios, and identify bottlenecks before they become critical.
[Try Tidely free for 7 days] and discover how much liquidity is tied up in your company.
Frequently asked questions about improving liquidity
How can a company improve its liquidity in the short term?
The fastest-acting measures are three: prioritize or postpone planned investments, issue invoices immediately after services are rendered, and consistently follow up on outstanding receivables. These steps require no third-party approval and show results within one to three weeks. Adjusting tax prepayments and requesting deposits for new orders provide additional impact within two to eight weeks. Canceling unused contracts is also worthwhile, but due to notice periods, it only takes effect after one to three months.
Which measure provides the most liquidity?
Usually, reducing capital tied up in working capital—i.e., shorter receivable terms, lower inventory levels, and faster billing for work in progress. For a company with 2.4 million euros in revenue, shortening the receivable term by just 15 days frees up around 98,600 euros without incurring interest.
How high should a company's liquidity be?
As a guideline: cash ratio (liquidity 1st degree) between 10 and 30 percent, quick ratio (liquidity 2nd degree) between 100 and 120 percent, and current ratio (liquidity 3rd degree) between 120 and 200 percent. These values vary depending on the source and industry. More meaningful than a single balance sheet date value is the trend over several quarters and a liquidity reserve that covers three to six months of fixed costs.
What is the difference between liquidity and cash flow?
Liquidity describes a stock, i.e., how much money is available at a specific point in time. Cash flow describes a movement, i.e., how much money has flowed in and out over a period. A positive operating cash flow improves liquidity, but does not guarantee it, because investments and repayments also tie up funds.
Is factoring worth it for improving liquidity?
Factoring is worthwhile if receivables are structurally long-term and the fee rate is lower than your financing alternatives. Calculate the fee as an annual interest rate and compare it with the terms of your operating credit line. As a permanent solution for a working capital problem, factoring is expensive; as an instrument for smoothing out seasonal fluctuations, it can make sense.
How often should I update my liquidity plan?
Operational 13-week planning is done weekly, while strategic 18- to 24-month planning is done monthly. During challenging phases, a daily view of the next 21 days is advisable. With a bank connection, updates happen automatically, limiting your effort to maintaining planned values.
Am I as a managing director required to perform liquidity planning?
For limited liability companies such as a GmbH, Section 1 of the StaRUG has been in effect since January 1, 2021. It requires management to continuously monitor for developments that could threaten the company's existence and to take appropriate countermeasures. Liquidity planning with an 18- to 24-month horizon is considered a core component of this duty. Failure to comply results in civil liability toward the company.
Sources
- Creditreform: Insolvencies in Germany, 1st Half 2026, 2026
- DIHK: DIHK Economic Survey Early Summer 2026, 2026
- KfW Research: Business Survey 2026, 2026
- Creditreform: Insolvencies in Germany, Year 2025, 2025
- Allianz Trade: Insolvency Study 2025, 2025
- Atradius: Payment Practices Barometer Germany, 2024
- European Central Bank: Monetary Policy Decisions of September 10, 2026, 2026
- KfW Research: KfW SME Panel 2025, 2025
- Federal Ministry of Justice: Corporate Stabilization and Restructuring Act (StaRUG), § 1, 2021
- PYMNTS and Visa: Growth Corporates Working Capital Index, 2026


